Author: RealEstateReport

  • DMV Housing Market Update: Buyers Gain Ground as July 2026 Home Prices Cool

    DMV Housing Market Update: Buyers Gain Ground as July 2026 Home Prices Cool

    DMV housing market report for July 2026: median home price dips to $660,000, inventory climbs, and the Contract Ratio signals a shifting advantage toward buyers across DC and Montgomery County. Brian Coester breaks down what this means for buyers, sellers, and homeowners across Washington, DC, Maryland, and Northern Virginia, with added context for readers following rec.homes and coester.com.

    The Washington, D.C. metro housing market took a step back in July, giving buyers a little more breathing room after a stretch of tight competition. According to the Greater Capital Area Association of REALTORS® (GCAAR) Executive Report, which tracks Washington, D.C. and Montgomery County, Maryland, the median sold price fell to $660,000 in July 2026 — down 4.5% from June and down slightly (0.8%) from July 2025.

    For anyone buying or selling a home in the DMV, here’s what the numbers actually mean. For more local market coverage, visit News, explore the DC Market page, or follow broader housing insights connected to Brian Coester, rec.homes, and coester.com.
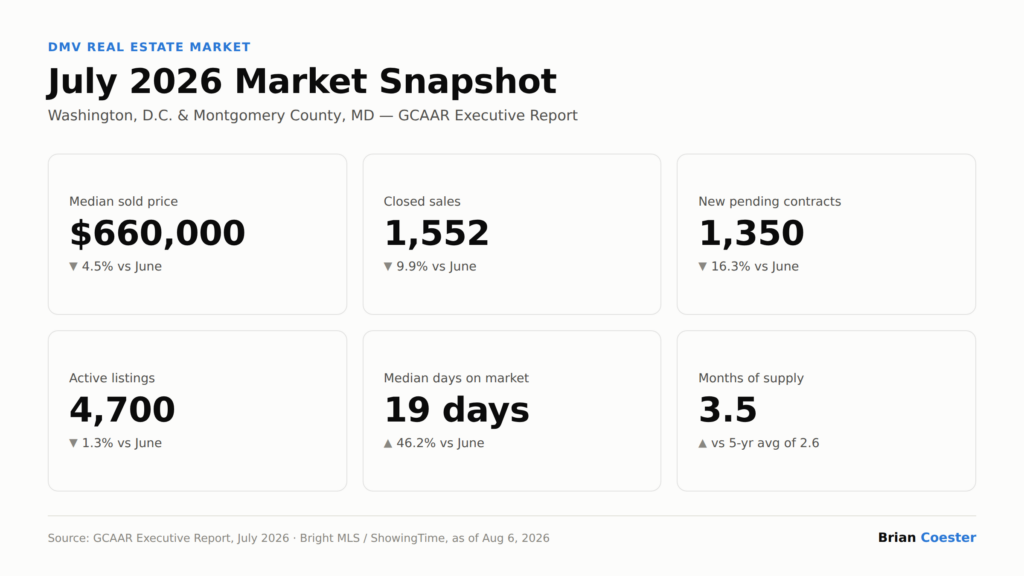
    July 2026 DMV Market Snapshot

    • Median sold price: $660,000 (down 4.5% month-over-month, down 0.8% year-over-year)
    • Average sold price: $870,069 (up 3.3% year-over-year)
    • Closed sales: 1,552 homes (down 9.9% from June, down 0.6% from July 2025)
    • Total sold dollar volume: $1.36 billion (up 2.4% year-over-year)
    • New pending contracts: 1,350 (down 16.3% month-over-month)
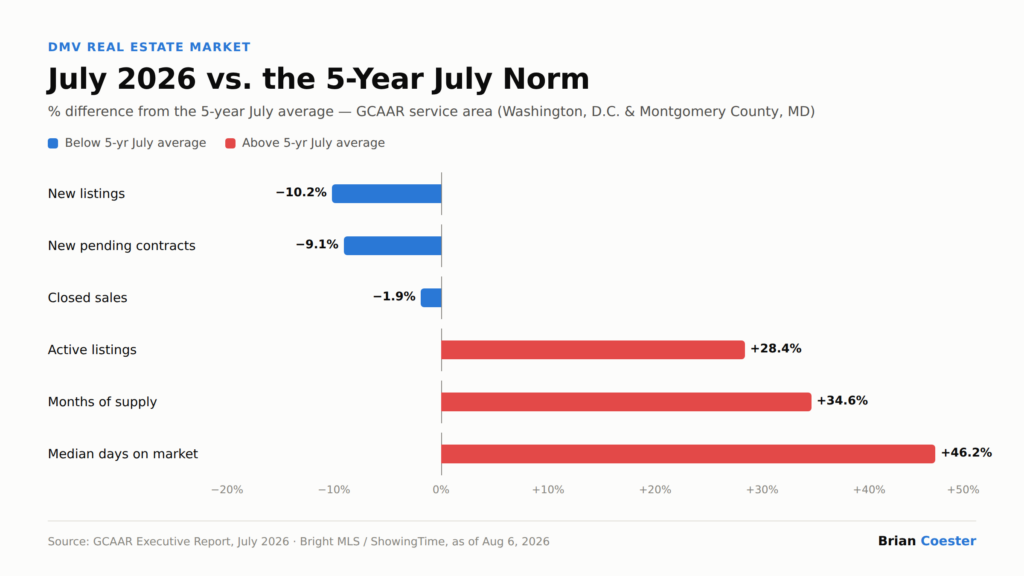
    • Active listings: 4,700 (down 1.3% from June, but still well above the 5-year July average of 3,661)
    • Median days on market: 19 days (up 46.2% from June)
    • Months of supply: 3.5 months (up from a 5-year July average of 2.6 months)

    Home Prices Are Easing, But Not Collapsing

    The median home price in the GCAAR service area — which spans Washington, D.C. and Montgomery County — sits at $660,000, essentially flat compared to a year ago but down notably from June’s pace. The average sold price tells a different story, up 3.3% year-over-year to $870,069, a sign that higher-end sales are still carrying weight in the market even as the broader median softens.

    Price per square foot echoes the same pattern: the median dipped slightly to $355 per square foot, while the average slipped 1.5% month-over-month to $402. Nothing here points to a price crash — it looks more like a market catching its breath after an unusually active spring.

    Inventory Is Building, Which Favors Buyers

    The clearest shift this month is on the supply side. Active listings stand at 4,700, well above the 5-year July average of 3,661, and months of supply climbed to 3.5 — up from a historical July average of just 2.6 months. More homes sitting on the market for longer gives buyers more room to negotiate.

    That shift shows up clearly in the Contract Ratio, which measures new pending contracts against active listings. In July, the ratio dropped to 0.33, down from 0.39 in June and 36% below the 5-year July average of 0.51. A lower Contract Ratio signals a market moving toward buyers, since fewer active listings are going under contract relative to what’s available. Homes are also taking longer to sell, with the median days on market jumping to 19 days — up nearly 46% from June — and the average climbing to 35 days, a third longer than the seasonal norm.

    How DC Compares to Montgomery County

    Within the GCAAR footprint, Washington, D.C. and Montgomery County are moving at somewhat different speeds:

    • Closed sales (year-over-year): D.C. saw a steeper decline than Montgomery County, which held closer to flat.
    • Active listings (year-over-year): Montgomery County inventory jumped sharply, while D.C.’s listing count actually edged down.
    • Average sold price (year-over-year): Montgomery County posted the strongest gains, outpacing both D.C. and the broader GCAAR average.
    • Days on market (year-over-year): Montgomery County homes are taking noticeably longer to sell than a year ago, while D.C. listings are actually moving a bit faster.

    The takeaway: Montgomery County is seeing more new supply and a slower pace of sales, while D.C.’s tighter listing count is helping keep its market comparatively brisk. Readers tracking nearby trends may also want to compare this update with our coverage of Maryland and Northern Virginia real estate conditions.

    What This Means If You’re Buying or Selling in the DMV

    For buyers, July’s data is encouraging. More inventory, longer days on market, and a Contract Ratio well below the historical average all point to more negotiating leverage than the DMV has offered in recent years — especially in Montgomery County, where listings have grown fastest.

    For sellers, pricing accurately and preparing a home well for market matters more than it did earlier this year. With homes taking roughly a third longer to sell than the seasonal average, overpricing carries a real cost in time and, often, in final sale price.

    Whether the market is shifting in your favor depends heavily on submarket, price point, and property type — the DMV is never one single market. If you’re weighing a move in the Washington, D.C. or Montgomery County area, now is a good time to get a clear read on how these trends apply to your specific neighborhood. Buyers and sellers comparing affordability should also review current Mortgage Rates and local reporting from Brian Coester.

    Data source: Greater Capital Area Association of REALTORS® (GCAAR) Executive Report, July 2026, provided by Bright MLS via ShowingTime, as of August 6, 2026.


    Ready to talk through what the July 2026 numbers mean for your home or your search? Reach out to Brian Coester for local, up-to-date guidance on buying or selling in the DMV. You can also learn more About, watch the TV Show, or Contact Brian directly for market insight tied to rec.homes and coester.com.

  • Who’s Actually Making Home Loans in 2026? Big Bank and Mortgage Company Production, By the Numbers

    The Big Picture: A $2.2 Trillion Market

    The U.S. mortgage market is on track for roughly $2.2 trillion in single-family originations in 2026, up from about $2.05 trillion in 2025, according to the Mortgage Bankers Association. By unit count, that’s approximately 5.8 million loans this year, up from 5.4 million in 2025.

    The split:

    • Purchase loans: ~$1.46 trillion (about two-thirds of the market)
    • Refinance loans: ~$737 billion

    Final 2025 HMDA data showed the average loan size nationwide was about $352,000, on an average property value of roughly $610,000 and an average rate of 6.78% for the year.


    Q2 2026: The Banks Came Back

    The second quarter was a breakout for depository banks. JPMorgan Chase, Wells Fargo, and Bank of America posted an average 32% quarter-over-quarter jump in mortgage volume — crushing analyst expectations of a 3% gain and industry forecasts of 6%. Banks reported strength among first-time homebuyers and in HELOC activity.

    Across the seven large banks tracked by KBW (Chase, BofA, Wells, Truist, PNC, Fifth Third, U.S. Bank), combined Q2 volume hit $56.1 billion, up from $46.4 billion in Q1 — an annualized run rate of roughly $225 billion from big banks alone.

    Q2 2026 Bank Production (Annualized Run Rate)

    LenderQ2 2026 VolumeAnnualized Run Ratevs. Year Ago
    JPMorgan Chase$17.2B~$69B+27%
    Wells Fargo$9.0B~$36B+22%
    Bank of America$8.2B (+$2.9B home equity)$33B + (12B HELOC)+28% QoQ mortgage growth

    The one caution flag: margins. Chase’s gain-on-sale margin fell roughly 45 basis points to 85 bps, meaning banks may be buying volume with price — good news for borrowers shopping rates.


    Annual Production Leaderboard: Dollars and Units

    Full-year 2025 HMDA data gives the cleanest apples-to-apples picture of who’s producing what. Loan counts for the banks are estimates based on average loan size (bank books skew jumbo/higher-balance).

    RankLender2025 Annual VolumeLoans (Units)Avg Loan Size
    1UWM (wholesale)$164.3B422,120~$389K
    2Rocket Mortgage$116.2B429,332~$271K
    3JPMorgan Chase$66.3B~120,000 (est.)~$550K (est.)
    4CrossCountry Mortgage$49.1B125,099~$392K
    5Wells Fargo$48.2B~95,000 (est.)~$500K (est.)
    6Bank of America$37.3B~75,000 (est.)~$500K (est.)
    7PennyMac~$33.7B

    Rounding out the top 10: U.S. Bank, Rate (formerly Guaranteed Rate), and Mortgage Research Center (Veterans United). The top 10 lenders combined control roughly 23.5% of all U.S. originations.

    What the numbers tell you

    Nonbanks still dominate volume, but banks are clawing back share. UWM and Rocket together produced over $280 billion and more than 850,000 loans in 2025 — more than the next five lenders combined. But Q2 2026 securitization and earnings data suggest banks took share back for the first time in years.

    Loan count vs. dollar volume tells two different stories. Rocket actually closed more loans than UWM (429K vs. 422K) but at a much smaller average size ($271K vs. $389K) — Rocket leans on cash-out refis and second liens, while over half of UWM’s book is purchase loans. Banks sit at the other extreme: fewer units, much larger balances, heavy jumbo concentration.

    Banks are the jumbo and HELOC channel. With Chase and Wells averaging an estimated $500K+ per loan, big banks are effectively competing for the move-up, high-balance, and equity-tap borrower — exactly the profile of much of the DMV market.


    Why This Matters in the DMV

    The Washington D.C. metro’s median-price housing stock sits squarely in the territory where bank jumbo pricing and nonbank purchase machines compete hardest. A few practical takeaways for local buyers and sellers:

    1. First-time buyer programs are getting real bank money behind them. Banks specifically credited first-time homebuyer strength for the Q2 surge.
    2. HELOC lending is accelerating. BofA logged its ninth straight quarter of home equity growth. With DMV homeowners sitting on substantial equity, home equity products are the fastest-growing way owners are tapping it without giving up a low first-mortgage rate.
    3. Margin compression = negotiating room. When gain-on-sale margins drop 45 bps in a quarter, lenders are competing on price. Shop at least three quotes — one big bank, one broker (the UWM channel), and one direct lender.

    Data sources: Q2 2026 bank earnings (JPMorgan Chase, Wells Fargo, Bank of America), Cleveland Research, KBW, BTIG, Mortgage Bankers Association 2026 forecast, and 2025 HMDA data via CFPB/Polygon Research. Unit counts for banks are estimates based on reported dollar volume and typical average loan size.

  • DMV Housing Market Hits $675K

    DMV Housing Market Hits $675K Median in June as Second-Half Slowdown Looms

    The DMV housing market closed the first half of 2026 with more momentum than many expected. According to Bright MLS, the Washington DC metro posted higher sales, more new listings, and a near-record median home price in June.

    For buyers and sellers in DC, Maryland, and Northern Virginia, the message is clear: the market is still active, but affordability pressures and rising inventory could make the second half of the year more competitive and more selective.

    June 2026 DMV Housing Market Snapshot

    Here are the key numbers from the June report for the DC metro area:

    • 5,274 closed sales, up 4.4% year over year
    • 5,452 new listings, up 3.7%
    • 11,168 active listings, up 9.0%
    • $675,000 median sold price, up 3.8% from June 2025

    That mix of rising sales, rising inventory, and rising prices shows that demand in the DMV is still absorbing new supply faster than many expected.

    Why Prices Are Still Rising

    Across the broader Mid-Atlantic, Bright MLS reported 23,278 closed sales in June, up 7.3% from a year earlier, with new pending sales up 3.9%. Bright MLS Chief Economist Lisa Sturtevant points to higher-end buyers as a major force behind the market, with less rate-sensitive households continuing to transact.

    That trend fits what many are seeing across the DMV. Move-up buyers and well-capitalized households in areas like Montgomery County, Northwest DC, and Northern Virginia’s close-in suburbs are continuing to buy, even in a mortgage rate environment above 6%.

    Some buyers also appear to be acting now because they no longer expect rates to fall meaningfully in the near term. Freddie Mac’s 30-year fixed averaged 6.43% in early July, which has shifted many households away from a wait-and-see strategy.

    Inventory Is Giving Buyers More Options

    One of the most important shifts in the market is inventory. Listing activity rebounded after a slow start to the year, and more homes on the market is creating better conditions for buyers while forcing sellers to compete more carefully.

    For buyers, a 9% increase in active inventory means more choices, less panic, and more room to negotiate on homes that sit longer. For sellers, it means pricing strategy and presentation matter more than they did during the ultra-tight market of recent years.

    If you’re following neighborhood-level trends, you can also explore our local market coverage for DC Market, Maryland, and Northern Virginia.

    What This Means for Sellers

    Sellers still have opportunity, but not every listing will command a premium. A near-record median price does not mean every home will sell at a near-record number. Well-prepared homes that are priced correctly and marketed effectively are still moving. Overpriced or poorly presented listings are more likely to sit.

    If you’re thinking about listing later this year, the current data suggests that sooner may be better than later. The buyer pool is still active now, but a second-half slowdown could reduce urgency if affordability continues to limit demand.

    What This Means for Buyers

    For buyers, this is a more balanced environment than the market offered in 2021 or 2022. More inventory creates more leverage, especially on listings that need updates, have been on the market for several weeks, or were priced too aggressively at launch.

    At the same time, the best homes are still attracting attention. Buyers who are financially prepared and focused on the right neighborhoods may find more opportunities now, but they still need to move decisively when strong listings hit the market.

    To track financing conditions alongside local pricing, visit our Mortgage Rates page.

    Why a Second-Half Slowdown May Be Coming

    Bright MLS does not expect the current pace to continue unchanged through the rest of 2026. Affordability remains the biggest constraint. At a $675,000 median price and mortgage rates in the mid-6% range, monthly payments are stretching many mid-market buyers.

    That matters because mid-market buyers drive transaction volume. If affordability weakens demand further in the second half, the result could be slower sales activity even if prices remain relatively firm in higher-end segments.

    Bottom Line for the DMV Market

    The first half of 2026 showed that the DMV real estate market remains resilient. Sales are up, inventory is improving, and home prices are still near record highs. But the second half of the year may look different as affordability pressures build and buyers become more selective.

    For sellers, timing and presentation matter. For buyers, selection is improving, but strong homes still move fast. In both cases, local strategy matters more than broad national headlines.

    Want more local market updates? Visit the News page for the latest DMV housing coverage.

    Wondering what your home is worth? Get an instant valuation with the Vestimate tool at rec.homes.

    Thinking about selling? Connect with the team at coester.com to discuss your next move.

    Want weekly video analysis? Visit the TV Show page or subscribe on YouTube.

    Source: Bright MLS June 2026 Housing Market Report, released July 10, 2026; Freddie Mac Primary Mortgage Market Survey.

  • Sweeping New Housing Law Takes Effect – And a Capital Gains Tax Exemption Could Be Next: What It Means for DMV Homeowners

    The biggest overhaul of federal housing policy in a generation is now the law of the land — and for homeowners across Washington, D.C., Maryland, and Virginia, a second wave of legislation targeting the capital gains tax on home sales could be an even bigger deal.

    Here’s what happened, what’s pending in Congress, and what it actually means if you own — or want to own — a home in the DMV.

    The 21st Century ROAD to Housing Act Is Now Law

    Just after midnight on Saturday, July 11, the 21st Century ROAD to Housing Act officially became law. President Trump declined to sign the bill — citing an unrelated dispute over election legislation — but did not veto it, allowing it to take effect automatically under the Constitution’s 10-day rule.

    Make no mistake about the scale here: the bill passed the Senate 85-5 and the House 358-32. In today’s Washington, those numbers are almost unheard of. Both parties wanted this on the books before the midterms, because housing affordability has become the number-one kitchen-table economic issue in the country.

    The law packs more than 40 provisions into a single package. The headlines for our market:

    A first-ever cap on institutional investors. Any investor that owns more than 350 single-family homes is now prohibited from buying more. It doesn’t force mega-investors to sell what they already own, but it draws a line that didn’t exist before. In competitive DMV submarkets where hedge-fund buyers have squeezed out families making offers with FHA and VA financing, that’s a meaningful shift at the margins.

    Faster, cheaper building. The law trims federal red tape, slims down environmental reviews, and pushes states and localities toward zoning that actually allows homes to get built. It also boosts manufactured housing and office-to-residential conversions — a provision with obvious relevance in downtown D.C., where office vacancy remains one of the biggest redevelopment stories in the country.

    Rehab money for aging housing stock. A new pilot program authorizes grants and forgivable loans to fix up older homes that have fallen into disrepair. Think of the rowhouse inventory in Baltimore, Northeast D.C., and older Prince George’s County neighborhoods — exactly the kind of housing this program was written for.

    One honest caveat: this law contains no new spending on affordable housing and doesn’t touch mortgage rates, which remain around 6.5% for a 30-year fixed. Supply-side reform takes years to show up in prices. But it’s the first serious federal move on housing supply in three decades, and it passed with real bipartisan muscle.

    The Next Fight: Killing the Capital Gains Tax on Home Sales

    This is the one every longtime DMV homeowner should be watching.

    Under current law — unchanged since 1997 — you can exclude up to $250,000 in profit on the sale of your primary residence if you’re single, or $500,000 if you’re married filing jointly. Anything above that gets taxed as a capital gain.

    Here’s the problem: home prices have roughly tripled since those caps were set, and they’ve never been adjusted for inflation. The National Association of Realtors estimates that about 34% of American homeowners — roughly 29 million people — would already exceed the $250,000 exclusion if they sold today. In high-appreciation markets like ours, the share is far higher. If you bought in Bethesda, Arlington, Capitol Hill, or Howard County in the 1990s or 2000s, there’s a very good chance you’re sitting above the cap right now.

    Two bills in Congress aim to fix it:

    The No Tax on Home Sales Act (H.R. 4327) would eliminate the federal capital gains tax on primary residence sales entirely. President Trump has repeatedly signaled support for the concept, saying his administration is looking at “no tax” on home sale gains. You’d still need to have lived in the home two of the last five years as your primary residence.

    The More Homes on the Market Act (H.R. 1340) takes the more moderate path: doubling the exclusions to $500,000 for single filers and $1 million for married couples, then indexing them to inflation going forward. It has bipartisan backing — 93 cosponsors, including 35 Republicans — and support from the National Association of Realtors.

    Neither has passed yet. Analysts see the doubled-and-indexed version as the more likely landing spot, potentially attached to a larger tax vehicle after the November midterms.

    Why this matters so much in the DMV: the capital gains cap creates what economists call a “lock-in effect.” Empty-nesters who’d love to downsize stay put because selling would trigger a five- or six-figure tax bill. That keeps family-sized homes off the market in exactly the neighborhoods where young buyers are hunting. If either bill passes, expect a wave of long-held DMV listings to finally hit the market — more inventory for buyers, and a genuine window of opportunity for sellers who’ve been waiting.

    The Broader Trump Housing Program

    Beyond the legislation, the administration has rolled out its own housing push over the past year:

    • An executive order restricting large institutional investors from buying single-family homes — the policy Congress just codified in the ROAD to Housing Act.
    • A directive for Fannie Mae and Freddie Mac to purchase $200 billion in mortgage-backed securities, aimed at pushing mortgage rates lower.
    • A March 2026 executive order cutting regulatory barriers to home construction, targeting stormwater and wetlands permitting, HUD program rules, and FHFA lending guidelines for manufactured housing.

    The White House credits these moves — along with falling rates — with reducing the annual cost of a typical new mortgage by nearly $5,000 since early 2025. Whatever your politics, the direction of federal policy is unambiguous: more supply, fewer investors competing with families, and cheaper borrowing.

    The Bottom Line for DMV Buyers and Sellers

    The timing of all this is remarkable. The same week the housing law took effect, NAR reported the median existing-home price hit a record $440,600 nationally — and DMV medians run well above that.

    If you’re a longtime homeowner: run the numbers on your potential capital gains exposure now, so you’re ready to move the moment Congress acts on the exemption. A change in the law could be worth tens of thousands of dollars on your sale — and could reshape the smartest timing for listing.

    If you’re a buyer: the institutional investor cap and the supply-side reforms are slow-burn wins for you. The bigger near-term variable remains mortgage rates. Getting pre-approved and knowing your true buying power — down to the specific neighborhood — is how you win in this market.

    If you’re just watching: this is the most active federal housing policy environment in 30 years, and the DMV — with its high home values, aging inventory, and office-conversion pipeline — sits at the center of nearly every provision.

    I’ll be tracking the capital gains bills closely as they move through Ways and Means and will break down exactly what passage would mean for Washington, D.C., Maryland, and Virginia homeowners the day it happens.


    Brian Coester is a licensed real estate broker serving Washington, D.C., Maryland, and Virginia. For a free home valuation, try the Vestimate AI valuation tool at rec.homes. Thinking about selling? Visit coester.com. For weekly DMV market updates, subscribe on YouTube.

  • DMV Housing Affordability: What Trump’s Housing Agenda Could Mean Locally

    Housing affordability is a national issue, but in the DMV it feels especially personal. Buyers across Washington, DC, Maryland, and Northern Virginia are dealing with high home prices, limited inventory, rising monthly payments, and the ongoing pressure of mortgage rates that remain elevated compared with the ultra-low-rate years. That is why any federal housing policy conversation matters here.

    In this episode, Brian Coester breaks down President Trump’s new housing agenda and looks at what the proposals could mean for the local housing market. The discussion focuses on affordability, housing supply, regulation, and the practical question many buyers and sellers are asking right now: will any of this actually make it easier to buy, build, or move in the DMV?

    What this episode covers

    • The administration’s stated goal of lowering housing costs
    • How expanding inventory could affect affordability
    • The role of zoning, permitting, and regulatory delays
    • Why construction costs still matter in local markets
    • Leadership changes at HUD and why they matter
    • What buyers, sellers, and investors in the DMV should watch next

    Why this matters in the DMV

    The DMV housing market has its own pressures. Land is limited in many close-in neighborhoods. New construction often faces long approval timelines. Entry-level buyers are competing in expensive markets from DC to Montgomery County to Northern Virginia. Even when national policy shifts, local affordability still comes down to supply, financing, and how fast homes can actually get built.

    That is what makes this conversation useful. It moves beyond headlines and looks at how federal ideas could connect to real conditions on the ground in the Washington region.

    Bottom line

    Housing affordability will not be fixed by one announcement or one administration. But for buyers, homeowners, sellers, and investors in the DMV, it is worth paying attention to any policy changes that could affect inventory, development costs, and the path to ownership. This episode offers a clear local lens on a national housing story.

    Read more DC market coverage | Explore Maryland housing news | See Northern Virginia updates | Track mortgage rate trends

  • Memorial Day in the DMV: Remembrance First

    Memorial Day in the DMV: Remembrance First

    Memorial Day in the DMV: Remembrance First

    Today starts with remembrance.

    Memorial Day tribute graphic for Brian Coester in the DMV

    We remember the men and women who never made it home. Not in the abstract. Not as a slogan. As sons, daughters, husbands, wives, friends, and neighbors whose lives were cut short in service to this country.

    Here in the DMV, that memory feels close. This morning, the presidential wreath-laying at the Tomb of the Unknown Soldier takes place at 11 AM in Arlington. That is local ground. Sacred ground.

    Memorial Day is not about the age of the country. It is about the cost of keeping it.

    This year marks 250 years since America’s founding. That matters. But Memorial Day is not really about the age of the country. It is about the cost of keeping it.

    A lot of people will gather with family today. A lot of people will enjoy the long weekend. That is part of American life too. But before any of that, this day should begin with a pause.

    Remember the fallen. Say their names if you know them. Hold space for the ones you do not.

    Thank you to our Gold Star families. And thank you to the fallen.

  • Capitol Hill Housing Market Update

    Capitol Hill Housing Market Update

    Browse Capitol Hill homes for sale if you want to see what buyers are actually comparing right now. When I look at the Capitol Hill real estate market, I focus on the same things I watch across the DMV every week: pricing discipline, inventory shifts, days on market, and how quickly serious buyers move when the right home hits. Capitol Hill remains one of the most durable submarkets in Washington DC because it offers a rare mix of location, architecture, walkability, and long-term demand. But it is not a one-speed market. Rowhouses, condos, renovated properties, and homes needing work are all trading on different timelines.

    That is why broad headlines about “the DC market” only get you so far. Capitol Hill behaves differently from Georgetown, Dupont, and many Northwest neighborhoods because buyer motivation here is often tied to lifestyle and scarcity. Proximity to the Hill, Eastern Market, parks, Metro, and neighborhood retail still matters. So does block-by-block presentation. If you are trying to understand where this submarket is heading, it helps to compare local movement against the broader Washington DC market instead of relying on national housing commentary.

    Pricing & Inventory

    Pricing in Capitol Hill is still being supported by limited supply, but buyers are more selective than they were during the peak frenzy period. That means well-prepared homes can still command strong numbers, while overpriced listings sit, reduce, and lose leverage. In this neighborhood, condition and layout matter a lot. A turnkey rowhouse with updated systems, strong natural light, and usable outdoor space is competing in a different lane than a dated property with functional issues or an awkward floor plan.

    Inventory has improved from the tightest points of the last cycle, which is healthy for the market. More choice gives buyers room to compare, and that changes negotiation dynamics. Instead of assuming every listing will attract multiple aggressive offers, sellers need to understand where their property fits in the current stack. Homes that are priced right and marketed well can still move quickly. Homes that test the market too high often end up chasing it down.

    Condos are also behaving differently from rowhouses. In many cases, Capitol Hill condos face more competition because buyers can compare monthly payments, building fees, and available alternatives across a wider part of DC. Rowhouses tend to benefit more from scarcity, especially when they offer classic Hill character with modern updates. That split is important for both buyers and sellers. You cannot price a condo strategy like a rowhouse strategy and expect the same result.

    For buyers, the takeaway is simple: there is more opportunity to negotiate than there was 18 to 24 months ago, but the best inventory still gets attention fast. For sellers, the message is even clearer: the market is rewarding precision, not optimism. If you miss the right pricing window, you usually give up more in later reductions than you would have by launching correctly from day one.

    Historic Washington DC rowhouses representing Capitol Hill housing stock

    Who’s Buying Here

    Capitol Hill attracts a broad but very intentional buyer pool. You see move-up buyers staying in the city, professionals who want walkability and transit access, Hill staff and policy professionals who value commute efficiency, and long-term buyers looking for a neighborhood with staying power. Investors are still present, but this is not a market driven mainly by speculative activity. Most demand here is lifestyle-based and long-hold oriented.

    That matters because lifestyle buyers tend to pay for fit. They are not just shopping by square footage. They are comparing block quality, renovation level, outdoor space, parking, basement utility, school considerations, and access to Eastern Market, Barracks Row, Lincoln Park, and Metro. In other words, the Capitol Hill real estate market is still emotional in the way strong urban neighborhoods often are, but buyers are backing those decisions with more analysis than they did when rates were lower.

    Financing also shapes the buyer pool more than it did in the ultra-low-rate era. Monthly payment sensitivity is real. Some buyers who would have stretched into a larger rowhouse a few years ago are now targeting smaller homes, condos, or properties with income potential. Others are using broader search strategies and evaluating financing options through platforms like rec.homes before deciding whether Capitol Hill, nearby Northeast, or close-in Northern Virginia gives them the best overall value.

    What Sellers Should Know

    If you are selling in Capitol Hill, presentation and positioning are doing a lot of the heavy lifting right now. Buyers still pay for quality, but they are less forgiving about deferred maintenance, clutter, dark photography, and vague pricing strategy. The sellers who outperform are the ones who treat launch week like it matters, because it does. Your first seven to ten days on market often determine whether you create urgency or start negotiating from weakness.

    That means getting the basics right before the home goes live: repairs, paint where needed, clean staging, sharp photography, and a pricing strategy tied to current competing inventory instead of last year’s peak sale down the block. Capitol Hill buyers know the housing stock well. They understand the difference between cosmetic updates and real value. If your systems, roof, windows, or lower level need work, the market will price that in quickly.

    Sellers should also pay attention to product type. A renovated two- or three-bedroom rowhouse with outdoor space may attract a very different response than a one-bedroom condo in a building with higher fees. The marketing, buyer targeting, and negotiation plan should reflect that. There is no one-size-fits-all playbook for this neighborhood. The right strategy depends on what you are selling, where it sits, and how it compares to the active competition buyers can tour this week.

    My advice is straightforward: do not price for the market you wish you had. Price for the market that exists now. If you do that, Capitol Hill can still be a very strong place to sell because demand is real and the neighborhood remains one of the most recognizable brands in DC housing.

    Looking to Sell in Capitol Hill?

    If you are thinking about selling, start with the local competition and the buyer profile your home is most likely to attract. Capitol Hill rewards smart preparation and disciplined pricing. It also punishes overreach. If you want to review current inventory, recent positioning, and what buyers are responding to right now, take a look at Capitol Hill homes for sale. That is the best place to begin before setting a pricing and launch strategy.

    Article Footer CTA

    Want help buying, selling, or understanding where the Capitol Hill market is heading next? Explore current listings, track weekly DMV market coverage, and connect with Brian Coester’s brokerage resources to make a smarter move.

  • Washington DC Real Estate Market Report: Neighborhood Trends, Prices & Buyer Outlook

    Washington DC Real Estate Market Report: Neighborhood Trends, Prices & Buyer Outlook

    If you want the short version of the Washington DC real estate market, here it is: demand is still there, pricing is highly neighborhood-specific, and buyers have more room to negotiate than they did during the peak frenzy years. That does not mean DC is suddenly cheap or easy. It means the market is acting more like a real market again, with better opportunities for informed buyers and sharper expectations for sellers.

    I have been watching and working in DMV housing for more than two decades, and DC continues to reward people who understand block-by-block differences. Capitol Hill does not behave like Georgetown. Dupont does not behave like Petworth. Condo inventory, rowhome demand, school preferences, commute patterns, and renovation quality all matter. In this report, I will break down what buyers, sellers, and investors should know heading into 2026.

    Washington DC skyline and city buildings

    DC Market at a Glance

    A data-first look at pricing, inventory, competition, and what it means for buyers and sellers in 2026.

    • Inventory has improved versus the ultra-tight conditions of the last two years, especially in condos and select upper-bracket segments.
    • Well-priced rowhomes in strong walkable neighborhoods still move quickly, particularly when condition and presentation are above average.
    • Condo buyers have more choices and more negotiating leverage than detached-home or rowhome buyers in many DC submarkets.
    • Mortgage rates remain a major affordability constraint, but stable rates are helping serious buyers re-enter the market with more confidence.
    • Neighborhood-level pricing gaps remain wide, which creates opportunity for buyers willing to compare trade-offs on size, location, and renovation level.

    One of the biggest mistakes people make is talking about DC as if it is one market. It is not. It is a collection of micro-markets with different buyer pools, different housing stock, and different price ceilings. That is why broad headlines can be misleading. A condo seller in Dupont may be dealing with a very different set of conditions than a rowhome seller on Capitol Hill or a luxury seller in Georgetown.

    For buyers, this is a market where strategy matters. Financing strength matters. Inspection posture matters. Patience matters. If you are buying in the right neighborhood for your goals, and you understand where leverage exists, there are real opportunities right now. If you are selling, the market is still rewarding quality, but it is less forgiving of overpricing and weak presentation.

    Neighborhood-by-Neighborhood

    Capitol Hill

    Capitol Hill homes for sale continue to attract buyers who want classic DC housing stock, walkability, and access to both neighborhood retail and the core employment base of the city. The rowhome segment remains the headline driver here. Updated homes with strong curb appeal and usable outdoor space still command serious attention, especially when they are priced in line with recent comparable sales rather than aspirational seller expectations.

    What I am seeing in Capitol Hill is a more selective buyer than we saw during the peak run-up. Buyers are still willing to compete, but they want value. Homes that need meaningful work, have awkward layouts, or push pricing too far above neighborhood comps can sit longer than sellers expect. For buyers, that creates openings. For sellers, it means the prep work matters more than ever.

    Georgetown

    Georgetown homes for sale sit in one of the most established and brand-driven submarkets in Washington. This is a neighborhood where architecture, prestige, and scarcity all support pricing. Buyers here are often less rate-sensitive than the broader market, but they are still disciplined. Luxury buyers want turnkey condition, strong finishes, and a product that feels worth the premium.

    Georgetown remains resilient, but it is not immune to overpricing. The gap between a fully updated home and an average-condition property can be significant. Sellers who assume the Georgetown name alone will carry weak presentation are making a mistake. Buyers, meanwhile, should pay close attention to renovation quality, parking, outdoor space, and the trade-off between charm and functionality.

    Dupont Circle

    Dupont is one of the clearest examples of how condo-heavy neighborhoods can behave differently from rowhome-driven markets. Buyers looking at Dupont Circle homes for sale are often comparing lifestyle, building quality, monthly fees, and walkability as much as they are comparing square footage. The neighborhood still benefits from strong demand drivers, but condo inventory can create more choice and more pricing spread.

    For sellers, that means positioning is critical. If your unit lacks updates or has a fee structure that pushes affordability, you need to be realistic. For buyers, Dupont can offer better negotiation opportunities than some rowhome neighborhoods, especially when a listing has been sitting and the seller is ready to move. The best values often come from buyers who understand building-by-building differences rather than shopping only by neighborhood name.

    Logan Circle

    Logan Circle continues to appeal to buyers who want central location, strong restaurant and retail access, and a polished urban feel. The housing mix gives buyers options, from condos to renovated rowhomes, but pricing remains premium because the neighborhood checks so many boxes. Buyers shopping Logan are often balancing convenience and lifestyle against space and monthly payment.

    The key in Logan is product differentiation. A well-designed condo in a strong building can perform very differently from an average unit with limited light or high fees. The same goes for rowhomes. Sellers who bring a clean, updated product to market can still do very well. Buyers should be careful not to overpay for style alone and should compare total monthly cost, not just purchase price.

    Petworth

    Petworth remains one of the neighborhoods buyers watch closely when they want more space and relative value compared with the city’s highest-priced core neighborhoods. Buyers looking at Petworth homes for sale are often seeking rowhomes, rental potential, or a better size-to-price ratio. That keeps demand steady, especially among move-up buyers and investors who understand the long-term appeal of the area.

    At the same time, Petworth is a market where condition and block matter a lot. Renovation quality can vary widely, and pricing discipline is important. Buyers should look carefully at mechanical systems, layout efficiency, and resale positioning. Sellers should understand that today’s buyers are comparing Petworth not only to nearby DC neighborhoods, but also to close-in Maryland and Northern Virginia alternatives.

    Condos vs. Rowhomes

    In 2026, the condo and rowhome segments are still telling two different stories in much of Washington DC. Condos generally offer more inventory, more price points, and more negotiating room. That can be attractive for first-time buyers, downsizers, or buyers who prioritize location over square footage. But condo buyers need to underwrite the full monthly cost, including fees, reserves, and any upcoming building assessments.

    Rowhomes, on the other hand, continue to benefit from scarcity and broader buyer appeal. They offer more control, more privacy, and often stronger long-term demand. The trade-off is a higher entry price and more maintenance responsibility. If you are weighing the two, the right answer usually comes down to budget, lifestyle, and how long you plan to hold the property.

    What Buyers Should Know in 2026

    Buyers have more leverage than they did during the peak competitive cycle, but that leverage is uneven. The best listings still move fast. The overpriced listings and the compromised listings are where negotiation lives. That means buyers need to be ready to act decisively when the right property appears, while also staying disciplined when a listing is clearly testing the market.

    If you are serious about buying, get fully underwritten, know your monthly payment range, and understand your neighborhood priorities before you start writing offers. This is also where a strong brokerage partner matters. If you are comparing options across the DMV, take a look at rec.homes for buyer tools, financing pathways, and broader brokerage support.

    What Sellers Should Know

    Sellers still have opportunity in DC, but the market is less forgiving than it was when almost everything moved on momentum. Today, pricing strategy is the first marketing decision. If you miss the market at launch, you can lose leverage quickly. Buyers are watching days on market, price reductions, and stale inventory much more closely now.

    The sellers who win are the ones who prepare the product, price from evidence, and understand the likely buyer pool. That means professional presentation, smart pre-listing work, and realistic expectations based on current neighborhood comps. In many cases, a clean launch with strong positioning will outperform an aggressive list price followed by cuts.

    FAQ

    Is now a good time to buy in Washington DC?

    For many buyers, yes. The better answer is that it depends on your budget, timeline, and neighborhood target. Compared with the most competitive recent years, buyers have more room to negotiate in parts of the market, especially in condos and listings that have lingered.

    Are DC home prices still rising?

    Some segments are still seeing price resilience, especially where inventory is limited and demand remains strong. But price growth is not uniform. Neighborhood, property type, and condition all matter more than broad metro headlines.

    Are condos a better value than rowhomes right now?

    In many cases, condos offer better entry pricing and more negotiating room. Rowhomes often offer stronger long-term demand and more control. The better value depends on your monthly budget, lifestyle, and hold period.

    Which DC neighborhoods should buyers watch?

    Capitol Hill, Georgetown, Dupont, Logan Circle, and Petworth all deserve attention, but for different reasons. Buyers should compare not just neighborhood names, but the specific housing stock, pricing trends, and trade-offs in each area.

    What is the biggest mistake sellers make?

    Overpricing at launch. In this market, the first impression matters. If a listing misses the market early, it can lose momentum and force price cuts that weaken negotiating power.

    Article Footer CTA: Want a clearer read on the Washington DC real estate market? Browse current listings on Coester, explore buyer resources on rec.homes, and follow Brian Coester for weekly DMV market analysis.

  • DMV Market Pulse — Week of May 25, 2026

    DMV Market Pulse — Week of May 25, 2026

    The DMV housing market is still moving, but buyers and sellers need to pay closer attention to pricing, inventory, and rate pressure than they did earlier in the spring. If you own a home and want a current benchmark before making a move, start with a free home value estimate here.

    This weekly pulse is built to give you the signal, not the noise. Here’s what matters right now across Washington DC, Maryland, and Northern Virginia.

    The Numbers

    MetricThis Week
    Median Price$649,000
    Active Inventory5,420
    Days on Market18
    30-Year Fixed Rate6.64%

    What Changed This Week

    • Inventory continued to build across key DMV submarkets, giving buyers more choices than they had earlier this year.
    • Median pricing held firm, which tells me demand is still there for well-positioned homes even as affordability stays tight.
    • Mortgage rates stayed in the mid-6% range, keeping monthly payment sensitivity high and making pricing discipline more important for sellers.

    For buyers trying to understand financing options, affordability strategy, and how to compete in this market, I recommend reviewing the tools and guidance available at rec.homes before you make your next move.

    What I’m Watching Next Week

    Next week I’m watching whether new listings continue to outpace buyer urgency in Montgomery County, Arlington, and parts of Northern Virginia. If inventory keeps rising while rates stay near current levels, buyers should gain a little more negotiating room, but homes that are priced right and show well will still move fast.

    Want to make a smart move in this market? Check your home’s value at Coester.com, explore your next-step options at rec.homes, and follow Brian Coester for weekly DMV market analysis built for buyers, sellers, and investors.

  • Coester Real Estate Services and REC.Homes Launch Vestimate, a New AI-Powered Home Value Tool

    Vestimate Launches AI Home Value Tool for the DMV Housing Market

    New AI Home Valuation Tool Targets Washington DC, Maryland, and Northern Virginia

    GAITHERSBURG, MD — May 12, 2026Coester Real Estate Services and Real Estate Connection (REC) have launched Vestimate, a new AI-powered home value tool built specifically for the Washington DC, Maryland, and Northern Virginia real estate market. The platform is designed to give homeowners, buyers, and sellers a more accurate view of property value in one of the nation’s most competitive housing regions.

    For readers following real estate news in DC, Maryland, and Northern Virginia, the launch highlights a growing shift toward hyper-local home valuation technology. Unlike broad national estimators, Vestimate is tailored to neighborhood-level pricing trends across Montgomery County, Gaithersburg, Clarksburg, Potomac, Bethesda, Northwest DC, Arlington, Fairfax, and Loudoun, where home values can vary sharply based on school boundaries, lot size, condition, and micro-market demand. That makes the platform especially relevant for homeowners, buyers, sellers, and investors who need a more accurate home value estimate in the competitive DMV housing market.

    Why This AI Home Value Tool Matters for DMV Homeowners

    Accurate home valuation has become a major issue in today’s DMV housing market as mortgage rates remain elevated, inventory stays tight, and pricing conditions shift from one neighborhood to the next. A more precise estimate can help homeowners decide whether to sell, refinance, renovate, appeal a tax assessment, or simply better understand their equity position in the current market.


    “Most online home value tools were built for the entire country, which means they’re not really built for anywhere,” said Brian Coester, founder of Coester Real Estate Services and host of the weekly TV show Real Estate Report. “Vestimate is different. It’s trained on the DMV, it’s reviewed by agents who actually sell here every day, and it gives homeowners a number they can trust, not just a generic estimate that’s $50,000 off the mark.”

    What Is Included in the Vestimate Home Value Report

    Every Vestimate® Report is delivered within 24 hours with no obligation, and gives homeowners three side-by-side scenarios so they can make a confident financial decision before they list:

    • As-Is Scenario (Sell Today) — What the home is worth and what the seller would net if they listed in current condition, with estimated sale price, selling costs, and net proceeds clearly broken out.
    • As-Repaired Scenario (Max Value) — What the home could sell for after strategic repairs and improvements, including estimated repair costs, selling costs, and the higher net proceeds that come with going to market in top condition.
    • Detailed Seller Net Sheet — A full line-item breakdown of every cost a seller will face, including listing and buyer agent commissions, transfer and recordation taxes, title insurance, settlement and closing fees, home warranty, loan payoff, and prepayment penalties — all flowing to a clear estimated net proceeds number.
    • Local Comparable Sales — Recent sales of nearby homes used to anchor the valuation, with distance and sale price for each comp.
    • Market Trend Analysis — Median sale price trends in the immediate submarket so homeowners can see where the market is moving, not just where it sits today.
    • Smart Recommendations — Actionable, agent-reviewed tips on what to fix, update, or stage to increase value and attract stronger offers.

    The report is free, requires no commitment, and is backed by REC’s local agent team, giving homeowners a direct path from online estimate to expert consultation. For buyers, the same valuation engine offers a clearer way to evaluate whether a property is priced appropriately before submitting an offer in a fast-moving DMV real estate market.

    How Vestimate Stands Out Among Online Home Value Tools

    As more consumers turn to online home value tools, this launch stands out because it combines AI with local real estate expertise rather than relying only on automated national data. That makes Vestimate especially relevant for homeowners in Washington DC, Maryland, and Northern Virginia who need market-specific guidance instead of a one-size-fits-all estimate.

    Built by a 20+ Year DMV Real Estate Expert

    Brian Coester has spent more than two decades in the DMV real estate and valuation industry, including building one of the country’s largest appraisal management platforms. That valuation pedigree is the foundation of Vestimate.

    “I’ve been on the appraisal side, the brokerage side, and the technology side of this industry for over twenty years,” Coester said. “Vestimate is what happens when you combine all three. It’s not a black box — it’s a tool that reflects how a real appraiser and a real local agent would actually look at a property.”

    The launch comes as DMV homeowners face elevated mortgage rates, limited housing inventory, and rapidly shifting neighborhood performance — conditions that make accurate, locally grounded home values more important than ever for refinancing, listing strategy, tax appeal, estate planning, and investment decisions. Readers tracking financing trends can also review the latest updates on the Mortgage Rates page for more context on affordability across the region.

    DMV Housing Market Impact

    For the broader Washington-area housing market, the release of Vestimate reflects how real estate technology is becoming more specialized and region-specific. In a market where pricing can change block by block, tools that account for local comparable sales and agent insight may play a bigger role in how buyers and sellers make decisions. Readers can explore more regional coverage on the Maryland, Northern Virginia, and DC Market pages.

    How to Access the Free DMV Home Value Tool

    Homeowners across DC, Maryland, and Northern Virginia can request a free home value estimate at vestimate.com. Agents and team members from REC are also available to provide follow-up comparative market analyses, listing consultations, and buyer representation through rec.homes and coester.com.

    For more local housing coverage, readers can also explore Brian Coester’s updates on the News page, review regional trends on the DC Market page, compare financing conditions on the Mortgage Rates page, learn more About Brian Coester, or visit the TV Show page for additional market commentary.


    About Vestimate

    Vestimate is an AI-powered home valuation platform focused on the Washington DC, Maryland, and Northern Virginia real estate market. Built and operated by Coester Real Estate Services and REC, Vestimate combines automated valuation modeling with local agent expertise to deliver home value estimates DMV homeowners can actually rely on. Learn more at vestimate.com.

    About Coester Real Estate Services

    Coester Real Estate Services, led by 20+ year industry veteran Brian Coester, provides full-service buyer and seller representation across the DMV. Brian is a licensed agent with Jason Mitchell Group and the host of Real Estate Report, a weekly TV show covering the Washington DC, Maryland, and Northern Virginia markets. Learn more at coester.com.

    About REC (Real Estate Connection)

    REC is a Gaithersburg-based real estate brokerage team serving buyers and sellers throughout DC, Maryland, and Northern Virginia. REC pairs experienced local agents with modern client technology — including AI-powered intake and valuation tools — to deliver a faster, more transparent transaction experience. Learn more at rec.homes.

    Media Contact

    Lucas Coester – Lucas@rec.homes

    Coester Real Estate Services / REC Email: brian@rec.homes Phone: 240-277-2900

    Web: briancoester.com | coester.com | rec.homes | vestimate.com

    Brian C. Coester

    Licensed Real Estate Broker— Maryland

    Coester Real Estate Services, LLC/ Team REC.Homes

    Download Vestimate Release

Subscribe